


Sure, you can challenge survivorship rights for a joint bank account in British Columbia. The law presumes an adult child holds a parent’s joint money in trust, so the survivor must prove a gift was intended. Fraud, undue influence, or misrepresentation at the time of account opening can be used as grounds to challenge something.
At Onyx Law Group, estate litigation lead Candace Cho, KC, was called to the BC bar in 2009, and our estate law lawyers have over 20 years of combined experience. We act in disputes over joint accounts and parental gifts, and we advise on wills that make a parent’s wishes clear. Whether you need to claim an inheritance or plan, reach out to us today to talk it through.
This article explains how BC courts treat joint bank accounts, what evidence decides a challenge, and what Winstanley v. Winstanley held.
Key Takeaway:
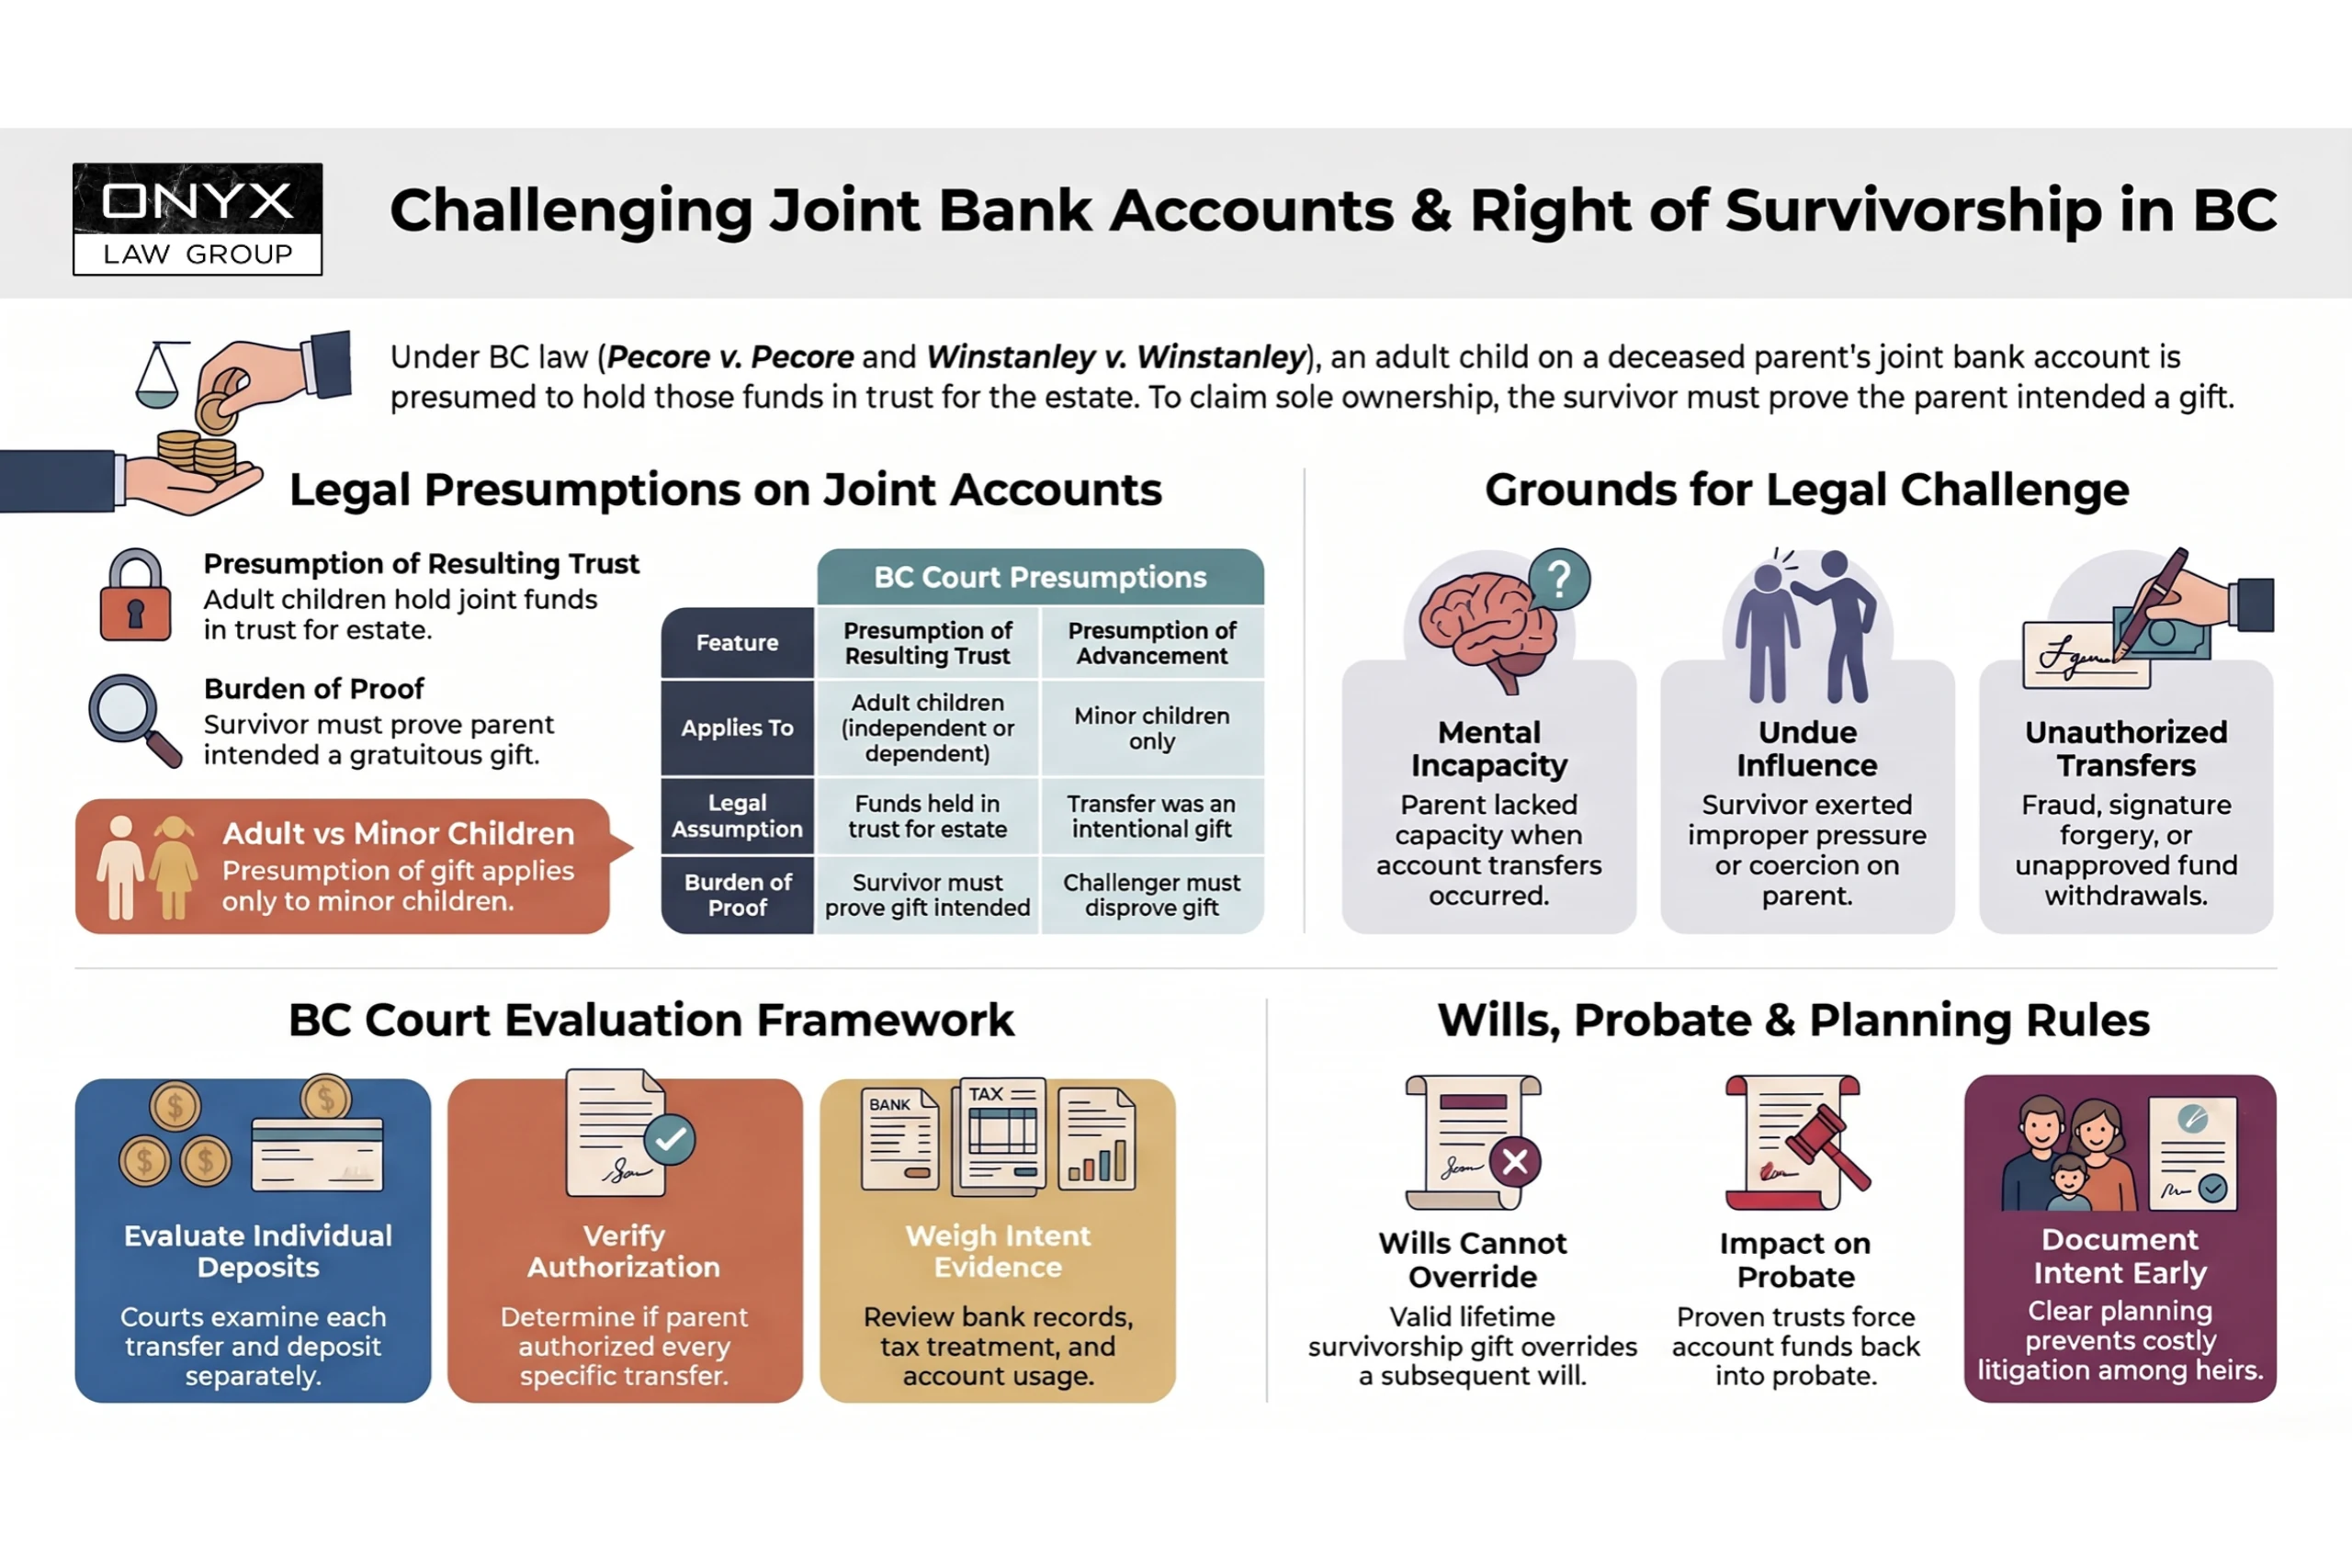
Yes. Under ancient law, an adult child who has a joint account with their parents is presumed to hold that money in trust for their parents. After the parent dies, the surviving owner must prove the parent meant to give them the balance. The Supreme Court of Canada set that rule in Pecore v. Pecore, and then the BC Court of Appeal applied it in Winstanley v. Winstanley.
What Is a Right of Survivorship on a Joint Bank Account?
A joint bank account has two or more owners, unlike an account with a sole owner. The financial institution keeps the written agreement they signed when they opened their account. That paperwork frequently involves signing a card. Each joint owner usually has the ability to pay bills and transfer money, depending on the terms of the account.

When one owner dies, ownership automatically passes to the other survivor. Under right of survivorship, ownership passes directly to the surviving owner, and that person then gets full ownership rights to all remaining funds. Joint tenancy land works similarly. Section 162 of the Wills, Estates, and Succession Act (WESA) refers to a right that passes on through survivorship for land ownership.
This article looks at both parents and adult children. Joint accounts held by married couples or other spouses, or involving a surviving spouse, raise separate questions that a lawyer should review. Pecore handled joint investment accounts as well as regular bank accounts, so the reasoning applies to other financial accounts too. Rules vary in different places, so this article talks only about British Columbia.
Legal Ownership Versus Beneficial Ownership
Ownership according to law is indicated by whose name appears on the account. Beneficial ownership looks into who owns the money and who stands to gain from it. On paper, the survivor has full ownership of the balance. In 2007 SCC 17 in Pecore v. Pecore, the daughter got legal ownership of the balance via survivorship rights. Was her father giving her an interest that was beneficial or setting up a trust for his inheritance?
Justice Rothstein wrote for the majority of the Supreme Court of Canada:
“While the focus in any dispute over a gratuitous transfer is the actual intention of the transferor at the time of the transfer, intention is often difficult to ascertain, especially where the transferor is deceased.”
Pecore v. Pecore, 2007 SCC 17, [2007] 1 S.C.R. 795, at para. 5
Because the owner who made the transfer has often died, courts rely on presumptions to fill the gap. A presumption under law is a supposition made when there’s insufficient or weak evidence regarding someone’s intent.
How the Presumption of Resulting Trust Works
A gratuitous transfer is one made for no payment in return. For these transfers, the presumption of resulting trust is the general rule. The person who received the property must show that it was given as a gift.
Before Pecore, a parent was presumed to have made a gift to an adult child. Pecore reversed that. The presumption of advancement applies only to transfers from parents to their minor children. It does not reach independent adult children, and the Court of Appeal confirmed in Winstanley that dependent adult children are treated the same way.
When a parent adds an adult child to a joint bank account, that parent is presumed to be holding that money in trust. Upon the death of the parent, the survivor must prove the parent intended to give them the right of survivorship over the remaining balance. The standard is the ordinary civil one, the balance of probabilities. The Supreme Court of Canada saw no reason to depart from it.
Resulting Trust and Advancement Compared
The two presumptions point in opposite directions, so the difference decides who has to prove what. This table lays out how each thing works using reasons summarized by Pecore and the Court of Appeal, according to Winstanley.
|
Point of Comparison |
Presumption of Resulting Trust |
Presumption of Advancement |
|---|---|---|
|
Starting assumption |
The person who received the property holds it in trust for the person who gave it. |
The transfer was a gift. |
|
Where it applies |
The general rule for gratuitous transfers, including a parent’s transfer to an adult child |
Limited to gratuitous transfers from parents to minor children |
|
Who must prove otherwise? |
The person who received the transfer must show that a gift was intended. |
The person challenging the transfer must rebut the presumption of a gift. |
|
Standard of proof |
Balance of probabilities |
Balance of probabilities |
|
Parent and adult child |
Applies whether the adult child is independent or dependent. |
Does not apply |
Grounds for Challenging a Joint Bank Account
According to British Columbia law, the right of survivorship in a bank account can be challenged under certain circumstances. The right of survivorship is a provision in a joint bank account that allows the surviving account holder to automatically inherit the account balance upon the death of the other account holder.
A challenge usually starts with the presumption of resulting trust, because it puts the burden on the surviving owner. Other grounds can also be raised alongside this presumption.
Undue influence is another claim that can stand alongside this one. In Winstanley, the child involved accepted responsibility for demonstrating that there was no undue influence at play. The Court of Appeal said that the trial judge should decide whether the presumption applied to the relationship in all ways.
The issue also includes whether the account owner had the mental capacity at the time those transfers happened. In Winstanley, the child called no witnesses to testify about whether the mother was aware of or had mental capacity at the time. Challenge can also be supported if there is fraud or falsification, like forging a signature card.
Winstanley spoke in the Supreme Court of British Columbia; that language is defined by WESA as the “court” for matters about property rights.
How a Court Decides a Joint Account Challenge

The Court of Appeal in Winstanley described the sequence of steps a judge presiding at a trial must follow. The steps below track its reasons and add the evidence Pecore says a judge may weigh.
Start With the Presumption of Resulting Trust
First, the judge instructs that there is no presumption of advancement between parents and adult children. The judge then applies the presumption of resulting trust to any gratuitous transfer to the child. It falls to the child to rebut the presumption for each transfer.
Separate Each Deposit and Transfer
Next, the judge identifies every disputed deposit and transfer. In Winstanley, there was a clear distinction between them, so lumping them together was a mistake. Each one needed its own look at the surrounding circumstances.
Ask Whether the Owner Authorized Each One
Then the judge must determine whether the parent authorized each deposit into the account and each transfer out of it. The child accepted at trial and on appeal that the child admitted that funds transferred into the joint account without proper authorization were held in trust.
Weigh the Evidence of Intent
Then the judge considers what the parents intended at the time of transferring something. Pecore says the evidence may include the wording of the bank documents and the control and use of the funds. It may also include a power of attorney, the tax treatment of the account, and later evidence that bears on the parent’s intention at the time. Both parties normally bring evidence on intent, whatever the legal burden. The trial judge decides how much weight each piece deserves.
Detailed paperwork from banks can be strong evidence that someone had intention. Having control of an account doesn’t settle things, and neither does having a power of attorney. A parent may add one child as a joint owner only to help with bills and day-to-day finances. The court considers the entire situation. In Madsen Estate v. Saylor, decided the same day, the Court held that the daughter had to rebut the presumption on the balance of probabilities. The text also says that the financial institution records were relevant evidence of her father’s intentions.
Test for Undue Influence
Finally, the judge decides whether the presumption of undue influence from Geffen v. Goodman Estate [1991] 2 S.C.R. 353 applies to the relationship and whether that influence has been rebutted. In Winstanley, the trial judge never made that finding, which was one reason the Court of Appeal ordered a new trial.
Can a Will Override a Right of Survivorship?
Not by itself. According to Pecore, rights of survivorship, both legal and equitable, attach when a joint account is opened. The gift of those rights is therefore made during the owner’s lifetime, not by will. If a survivor can prove that this gift was intended by the parents, then a later will cannot undo that gift.
If survivors cannot prove otherwise, then the balance goes into the estate of the deceased parent and is distributed according to that parent’s will.
WESA also covers joint accounts if the account owners die very near to each other time-wise. Under section 10(2), if no one can show that one joint owner outlived the other by five days, the account is split in half. One half passes as if each owner had survived the other. Section 10(4) also notes that this rule does not impact laws related to resulting trusts.
Where Probate Fits In
Probate is the legal process through which someone gets permission from a court to manage an estate. A joint account that passes by survivorship generally moves outside the estate, so it does not go through the probate process. When a court declares a resulting trust, then that remaining balance is considered part of the estate assets.
The Probate Fee Act charges no fee on an estate worth $25,000 or less. It sets $6 for every $1,000 or part of $1,000 between $25,000 and $50,000. It sets $14 for every $1,000 or part of $1,000 above $50,000. The fee is calculated based on the gross value of the property that goes to the personal representative.

What Happened in Winstanley v. Winstanley

Winstanley v. Winstanley, 2017 BCCA 265, was a dispute between two brothers over their mother’s estate. Jessie and Harold Winstanley got married in 1961 and separated in 1996. Carl, their younger son, lived with Jessie from 1994, and in 1996 the two opened a joint bank account to manage household expenses together.
Harold passed away on June 7, 2011. Under his will, he left his entire estate to Jessie. It totaled $244,087, and all of it was deposited into the joint account. Jessie had a stroke two months later and passed away on October 4, 2011. Her will left the residue to her older son, Andrew, and acknowledged that she held assets jointly with Carl that would not form part of her estate. After her death, Carl paid Andrew $204,200 from the account as an advance on his inheritance.
Andrew sued, arguing that Carl had deposited and moved Jessie’s money without her authority. He was left with $74,887.32 as his final claim. The trial judge dismissed the case except for the $40,000 that Carl had agreed to pay. The Court of Appeal allowed the appeal and, in its words, “most reluctantly” ordered a new trial. It found seven disputed deposits and transfers that the judge had to examine one by one. It could not decide the credibility questions on its own.
Court of Appeal Disagrees With the Trial Judge’s Analysis
Andrew appealed, arguing that the trial judge failed to properly apply the presumptions of resulting trust and undue influence to the transfers in dispute. The Court of Appeal allowed Andrew’s appeal and reluctantly ordered a new trial. There was some evidence from which the judge could have concluded Carl had authority to deposit to, and withdraw from, the Joint Account, but the Court of Appeal was not in a position to make the credibility and factual findings necessary to determine whether Carl had rebutted the presumptions of resulting trust and/or undue influence. Carl’s cross-appeal regarding the $40,000 payment was dismissed, with there being no basis upon which the appellate court would interfere with that aspect of the trial judge’s order.
Ready to Challenge or Protect a Joint Bank Account?
A joint account looks simple on paper, but BC courts look behind the names to see what the parent intended. Courts presume an adult child named on a parent’s account holds the money in trust, and the survivor must prove a gift. Talk to the right lawyer early if you or any family member is involved in a dispute. Collect important papers that the court will consider when weighing.
Our estate litigation team is led by Candace Cho, KC, who has co-chaired the Trial Lawyers Association of BC’s Estate Litigation Essentials courses multiple times since 2020. We help families who have disputes over joint accounts, and we also assist parents in putting together estate plans so that their intentions are clear. Contact Us Today to book a consultation.
Frequently Asked Questions
Our estate lawyers deal with disputes about joint bank accounts and inheritance gifts from parents; that’s why we can give straightforward answers to such questions. The answers below draw on the Supreme Court of Canada’s decisions in Pecore and Madsen and the BC Court of Appeal’s decision in Winstanley. They are general information, not advice on your situation.
What Is the Presumption of Resulting Trust for a Joint Bank Account?
If a parent gives money directly to an adult child, under BC law that child is presumed to be holding that money in trust. Adding a child to a joint account is one example.
Does the Presumption of Advancement Apply to a Parent and an Adult Child?
No. Under Pecore, the presumption of advancement is limited to transfers from parents to minor children. For adult children, whether independent or dependent, the presumption is one of resulting trust.
Who Has to Prove What in a Joint Account Dispute?
The surviving account holder must show the parent intended to grant them the right of survivorship over whatever was left behind. The standard is the balance of probabilities, the ordinary civil standard.
Can a Will Override a Right of Survivorship?
It’s not something that happens on its own; survivorship becomes part of your account as soon as you open it. If a survivor cannot show that someone gave a gift on purpose, then the balance of that thing goes into the inheritance and is distributed according to the will.
What Evidence Do Courts Consider?
Courts can consider the bank documents, as well as who had control and used the money, and also check for any power of attorney. They can also weigh the tax treatment of the account and later evidence that bears on the parent’s intention at the time. The judge decides how much weight each piece bears.
Where Is a Joint Account Challenge Heard?
Winstanley spoke at the Supreme Court of British Columbia before going on to the Court of Appeal. A lawyer can tell you which court would be appropriate for your claim.
What Did Winstanley v. Winstanley Decide?
Court of Appeal requested a retrial because the trial judge did not examine each deposit and transfer separately. The judge also hasn’t yet decided whether the child has rebutted presumptions of resulting trust and undue influence.
This page is the responsibility of Onyx Law.
The information on this page is general legal information about British Columbia law, not legal advice for any specific situation. Reading this page does not create a solicitor-client relationship. BC law changes, and the procedure that applies to a specific situation depends on facts not covered here. For advice on your situation, consult a qualified British Columbia estate lawyer directly. Past results, illustrative scenarios, and reference to typical fact patterns do not guarantee similar outcomes in any specific case.