


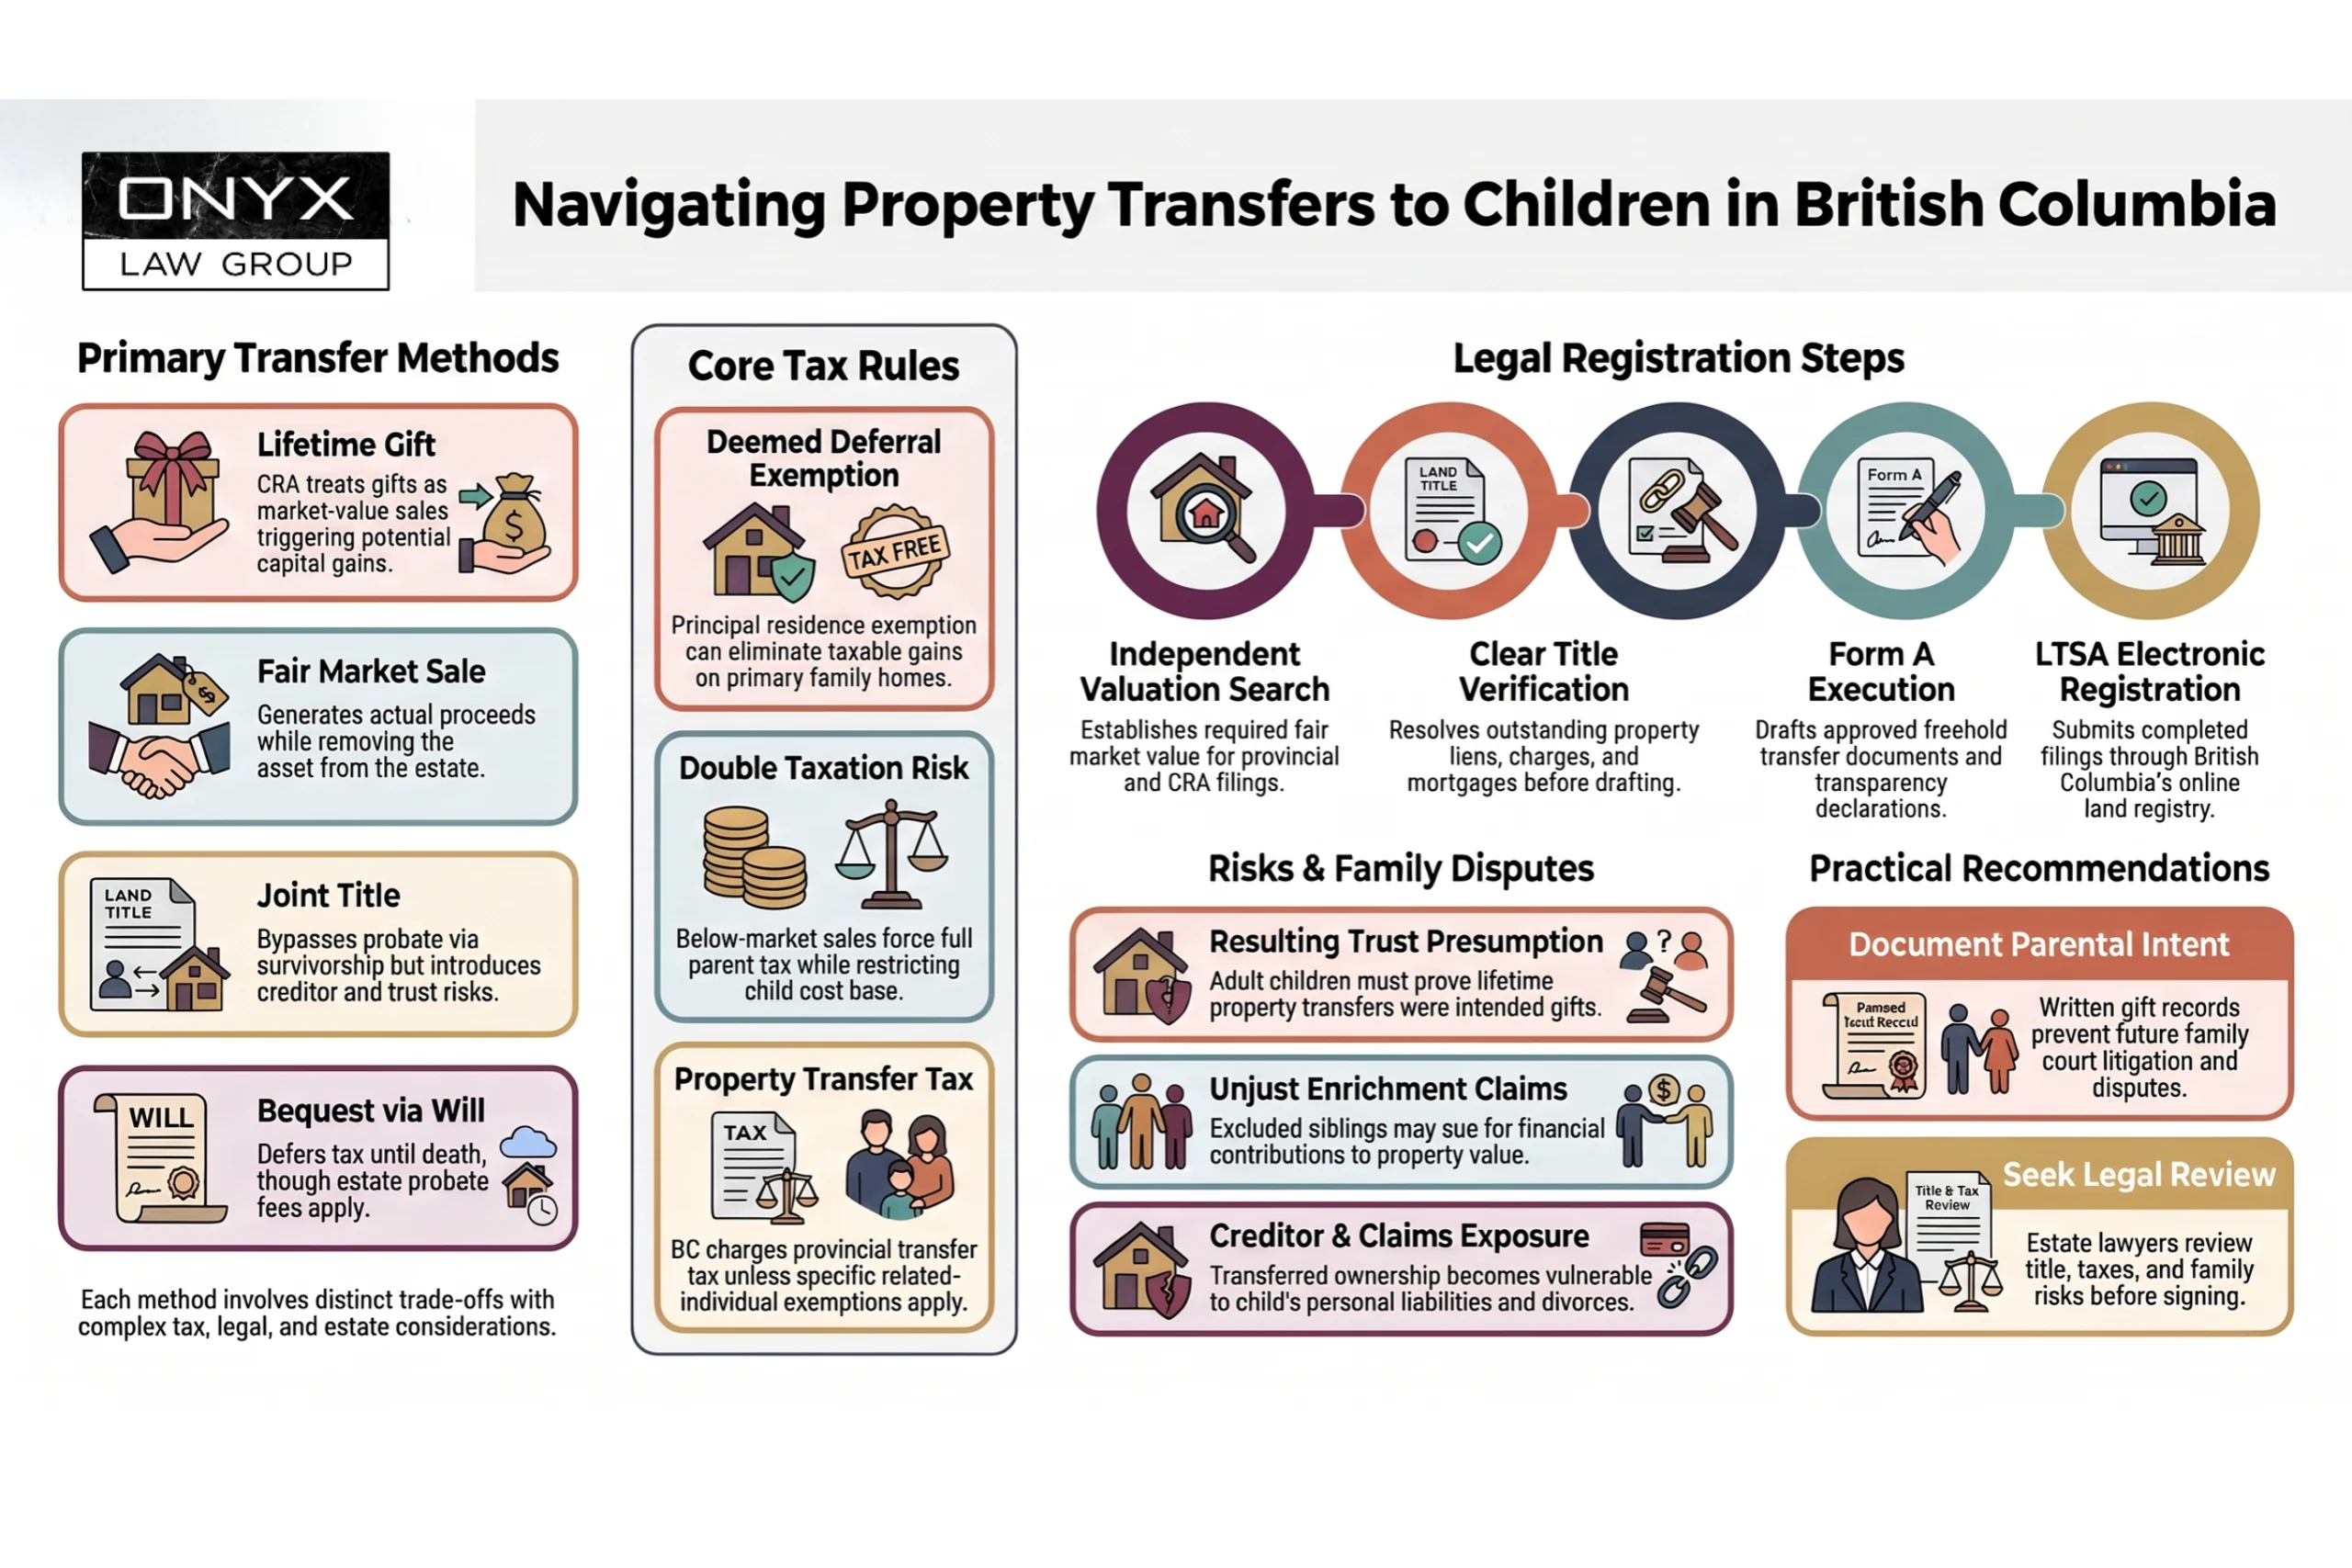
Transferring property to a child happens in Canada by means of a gift, a sale, or through a will. The Canada Revenue Agency treats a gift as a sale at fair market value, so capital gains tax can apply. In BC, the property transfer tax may be exempt for a family home, and the principal residence exemption can reduce the gain.
The lead lawyers at Onyx Law have over 20 years of combined experience in family and estate law, and Candace Cho, KC, who leads our estate litigation team, was called to the British Columbia bar in 2009 and has co-chaired the Trial Lawyers Association of BC’s Estate Litigation Essentials course four times since 2020. We review titles in our estates and trusts lawyers review title, tax exposure and parental intent before to signing, and we act if there is a dispute among family members regarding transfers. When deciding between gifts, sales, or shared titles with your child, talk to our team first.
This article explains how each transfer method is taxed, what British Columbia requires for registration, and where family disputes begin.
What Is the Legal Process for Transferring Property Ownership From Parent to Child in Canada?
Transferring property from parents to children isn’t just about changing names on a deed; it’s a formal legal process. Location determines the land registration process and the taxes, because property law is largely provincial. In British Columbia, the land registry office is the Land Title Office, run by the Land Title and Survey Authority (LTSA).
To transfer ownership, the lawyer first drafts a document called a Form A Freehold Transfer, which British Columbia refers to as a transfer of land. Section 185 of the Land Title Act requires a freehold transfer to use the approved form and fit on a single page. Proof of ownership is also important, and a title search should reveal any liens or charges against the title for the property. A legal professional may also request a family gift affidavit to record that the parent meant a gift. The official BC sources reviewed here do not list one as a filing requirement.
Then the lawyer fills out the tax return that goes along with the transfer paperwork. Ontario calls their version something called Land Transfer Tax, but British Columbia charges a Property Transfer Tax. You or your legal professional file that return online, and any exemption is claimed on it. The package also includes a declaration of transparency for the Land Owner Transparency Registry, which the child signs as the new owner.
Then the lawyer submits the application electronically to LTSA for registration. As of April 1, 2026, the LTSA fee listing charges $83.82 for a title transfer. The LTSA says most applications register within 10 to 15 business days. Eligible users who apply through the BC Services Card app usually register in 2 business days. Mortgage consents, tax questions, or title problems can stretch that timeline, so a lawyer usually resolves them before filing.
Tax Implications When Transferring Property from Parent to Child in Canada
The tax consequences vary depending on whether something is given as a gift, sold, or inherited. The Canada Revenue Agency regards a gift that lasts a lifetime as being sold at fair market value regardless of whether any money is exchanged. Under section 69(1)(b) of the Income Tax Act, a gift or below-market sale gives the parent deemed proceeds at fair market value.
Capital gains tax is usually the biggest single cost associated with transfers over a lifetime. The gain is calculated as the fair market value minus adjusted basis, and half of that gain is added to the taxable income of the parent. The Federal Government has confirmed in Budget 2025 that it will not go ahead with the proposed increase of that rate. A gift counts as a disposition, so the parent reports it on Schedule 3 of that year’s tax return.
Canada has no gift tax, so the child does not pay tax on receiving the property. Canada also has no estate taxes, but at death the deceased is taxed on the deemed sale of capital property, and BC charges probate fees. Fees occur during estate administration and settlement; this is something that transfers of wealth made over one’s lifetime often avoid.
Tax treatment is different for inheritance compared to receiving a gift for the child. Upon death, the CRA treats the property as if it were sold for its fair market value and the estate pays the capital gains tax. Once the property passes to the child, the child takes a cost base equal to that value, which can reduce future gains.
Understanding Capital Gains Tax on Gifted Property
The adjusted cost base is the original purchase price plus eligible costs, such as legal fees and capital improvements. When a parent gives a house as a gift, the CRA treats that as if they sold it for its current market value. Picture a rental property bought for $300,000 and worth $800,000 on the day of the gift. The total gain is $500,000 and $250,000 of that goes on to be taxable for the parent.
The rules that apply to transactions involving children differ from other parts of the same law. Under section 69(1)(c), a child who receives property through gifts takes ownership at the price that the property would fetch on the open market. A sale below fair market value gets no such adjustment, so the child’s cost is only the price actually paid. That gap creates double taxation, since the parent is taxed on full value and the child’s gain starts from a lower cost. A parent who sells an $800,000 home to a child for $1 is taxed as if they had received $800,000. The child’s cost is still $1, so the same value is taxed again on a later sale.
The principal residence exemption can change the result for a family home. Under section 40(2)(b) of the Income Tax Act, a formula based on designated years reduces the gain on a principal residence. If the property qualifies, enough designated years can bring the taxable gain to nothing. The CRA explains reporting and designation on its principal residence exemption page, where Form T2091(IND) designates the property. The exemption covers the gain only, so legal fees and other transfer costs remain.
Many families think that giving gifts is tax-free because there is no sale involved. For tax purposes, gifts and sales at less than market value are considered as sales at full value. Tax-free rollovers do exist for some kinds of transfers like those involving common-law partners, but they usually don’t apply to transfers of property from parents to children. Transfers that aim to reduce tax or probate costs also carry some risks such as triggering capital gains tax during the parent’s lifetime, losing control of the property once the child holds title, and exposing the property to the child’s creditors or family law claims.
In BC, a parent who transferred property to their children to move ahead of debts may not be able to recover those payments. Here is a comparison of the four main ways that parents transfer property to their children. It looks at tax results, probate implications, risks from creditors, and risks of being taxed twice for each method.
|
Transfer Method |
Tax Result for the Parent |
Probate Effect |
Creditor Exposure |
Double-Taxation Risk |
|---|---|---|---|---|
|
Gift during life |
Deemed sale at fair market value, with 50% of the gain taxable unless the principal residence exemption applies |
The property passes from the parent’s estate. |
Open to the child’s creditors and family law claims once the child holds title |
Low, because the child’s cost is set at fair market value |
|
Sale at fair market value |
Real proceeds, with the same gain calculation and the same exemption options |
The property leaves the estate, and the sale proceeds remain with the parent. |
Open to the child’s creditors, and the child’s lender may hold a mortgage |
Low, because the price paid equals fair market value |
|
Adding the child to title |
May be treated as a gift of a share; confirm the result with a tax professional. |
A right of survivorship can pass the parent’s share outside the estate, but the resulting trust presumption can revert it. |
The child’s creditors can reach the child’s interest, and the parent may not be able to sell alone |
Depends on the structure; therefore, a tax professional should review it first. |
|
Leaving it in a will |
No tax during life, and the estate pays on the deemed disposition at death |
Probate fees may apply to the estate. |
None while the parent is alive |
Low, because the child takes the cost base at fair market value on death. |
Common Challenges and Disputes in Property Transfers Between Parents and Children
Property transfers between parents and children can lead to disputes among siblings and other relatives. Some begin with situations involving undue influence and capacity where a parent is either pressured into decisions or could not make legal decisions. People come from unjust enrichment due to issues with ownership and valuations or lack of good documentation regarding intentions of parents.
The Supreme Court of Canada case set the starting point in Pecore v. Pecore, 2007 SCC 17. The court ruled that when someone transfers something free of charge, this is presumed to be done under an arrangement called a resulting trust in favor of the person who gave the thing away. The person who received the property must show that a gift was intended. It limited the presumption of advancement to transfers from parents to minor children. A court starts at the presumption of resulting trust when the person becomes an adult according to BC.
Preventing problems is much easier than solving them, and prevention begins long before people sign anything. Clear written documentation, legal advice for both generations, and open talks with every sibling reduce future disputes. A shut-out sibling may start proceedings contesting a gift, which a lawyer can mediate or litigate.
Legal Remedies for Unjust Enrichment Claims
In family property transfers, unjust enrichment occurs when one person benefits unfairly at another person’s expense. Imagine a parent giving the family house to one child but having another pay the mortgage payments over many years. The excluded child could argue that the transfer left them out of pocket for no fair reason.
Courts in Canada can respond to a successful unjust enrichment claim in more than one way. A court may order the benefiting child who benefits financially to pay the sibling monetary compensation to other siblings for their contributions as well. Alternatively, it may impose a constructive trust so the sibling shares in the property or its value. The remedy depends on the circumstances, the property’s worth, and the fairness of the original transaction. An early talk with an estate lawyer helps families spot a possible claim and weigh the legal implications.
Common Reasons for Transferring Property to Children
Statistics Canada found that 17.3% of residential properties owned by people born in the 1990s were co-owned with parents in 2021. Excluding Quebec and Saskatchewan, the rates were higher, especially in expensive urban areas such as Vancouver and Victoria. Parents act for several reasons, from estate planning and tax planning to financial compensation and investment goals.
Many parents want a smooth inheritance, with the family home staying inside the family. Moving the home to a child during life may reduce probate fees, but it can shift the tax burden to the parent. Any way to avoid probate should be weighed against the tax and control costs described above. A good estate planning checklist likes to put transfers alongside wills, powers of attorney, and beneficiary designations. Some families also wonder how transfers affect their government benefits, and they need help getting specific advice about which particular program this applies to.
Other parents also want to help their grown children into the real estate market or to become financially stable. A child who takes on a mortgage must earn sufficient income to carry the mortgage payments. The child should also consider the tax considerations of buying and later selling the home. The parent’s help may be a gift, a sale, or a co-owned title that helps the child qualify with a lender.
A final group transfers investments, rentals, or commercial real estate so as to hold on to important family assets. The child also starts managing property along with receiving rental income. Income from that source shows up on the child’s tax return, and later selling something received would trigger capital gains tax on any appreciation in value since when you transferred it.
How Transferring Ownership of Property from Parent to Child Works in Canada
Transferring property to a child takes planning to avoid surprise taxes, legal disputes, and financial risk. As our Principal Lawyer, Candace Cho always explains,
Transferring property to a child can be a meaningful financial decision, but without proper planning, it may lead to unexpected tax and legal consequences.
The steps below show how a typical transfer moves from the first decision to the last update of records.
Step 1: Decide on the Type of Transfer
First, decide on the type of transfer, because the choice drives every later step. You can gift the property, sell it, or leave it in your will to go to someone else after you die, and each of those choices results in different tax results. Gifting involves no payment, but it still triggers the deemed sale at fair market value. A sale at fair market value is standard for the CRA. A will ensures that property remains in your name until your child inherits from you.
Step 2: Check Provincial and Municipal Laws
Check the provincial and municipal rules that apply where the property is located. Property transfer rules, provincial laws, and local taxes vary across Canada, and British Columbia has its own registration and tax rules. A real estate lawyer can verify which exemptions apply to your property and family.
Step 3: Hire a Real Estate Lawyer
Then hire an estate and trust lawyer who is real. The lawyer handles the Form A transfer process, researches the title, and then files the deed tax return before submitting the registration. The lawyer also makes sure that any exemptions claimed match up with actual facts; this protects the family if the tax officials start asking questions later on.
Step 4: Obtain a Property Appraisal
After that, obtain a valuation, since the CRA and the property transfer tax both need the property’s fair market value. The BC government says a non-arm’s-length transfer can use a recent independent appraisal or the BC Assessment valuation. An appraisal gives the current market value of a property, and an agent’s opinion may serve as a good starting point.
Step 5: Pay Applicable Taxes and Fees
Then handle taxes and fees in the right sequence; this order differs for each specific tax. The property transfer tax return goes in with the registration, and any tax owing is paid to the Ministry of Finance. Capital gains tax comes later, because the parent reports the disposition on the tax return for the year of the transfer. A tax advisor can estimate the gain before you sign, so the family avoids a surprise bill the following spring.
Step 6: Update the Property Title and Register the Transfer
Once the property transfer tax is paid with the return, you can then register the transfer of property with the provincial land registry office. They will then change the title to reflect the new owner’s name. You may also want to do an extra check called a title search to verify that there are no legal disputes or unpaid bills on the property.
Step 7: Update the Records and Notify Stakeholders
After the transfer, the child should be aware of their future tax obligations. For instance, a child who received a house from a parent ended up renting it out rather than living in it. Because the property was not their principal residence, the rental income had to be reported to the CRA, and when the child eventually sold the property, capital gains tax applied. This shows that understanding continuing tax responsibilities is important before someone receives a property.
We recommend updating your will and estate plans to ensure that assets are properly considered as part of future inheritance arrangements. Also, the child should update their homeowner’s insurance policy to show the correct new ownership.
Additionally, all utility accounts, including electricity, water, gas, and internet, should be transferred to the child’s name. Failure to update this information may lead to billing problems or complications when it comes to dealing with any damage to the house. Sometimes, you may also need to make equitable financial arrangements to compensate other children who might not be interested in inheriting the property.
Legal Aspects of Property Ownership Transfer
Federal and provincial rules both govern how families transfer real estate in Canada, so costs depend on the property’s location. The federal Income Tax Act sets the capital gains treatment, while provincial regulations control land registration and transfer taxes. Everywhere in Canada, the transfer is a real estate transaction that must be documented and registered. The CRA also considers it to be sold at fair market value.
British Columbia has a parent-to-child exemption from property transfer tax, with specific conditions. Under section 14(3)(b) of the Property Transfer Tax Act, a transfer to a related individual, which includes a child, can be exempt. The land must have been either person’s principal residence for at least 6 continuous months before the transfer. The Act defines a principal residence as a parcel the person usually lives in, with improvements for three or fewer families. If the parcel is larger than 0.5 hectares, only a partial exemption is available for the residential part, and the recipient must be either a Canadian citizen or a permanent resident.
BC government’s guidance instructs you to choose Exemption 05 for Related Individual Principal Residence on the return. Another part of section 14(3) includes both family farms and vacation homes. If no exemption applies, the rates start at 1% for amounts up to $200,000 and go to 2% for amounts up to $2 million. Above that, the rate is 3%, and a further 2% applies to the residential value above $3 million, based on the property transfer tax page as updated in December 2025.
Adding a child to a title raises separate issues about joint tenancy versus tenants in common. Choosing something different affects what happens to that parent’s share if the parent were to die. Survivorship rights allow parents’ shares to bypass the estate and also avoid probate fees. The resulting trust presumption can still apply, so the child may hold that share for the parent’s estate. If evidence shows that the parent intended this as a gift, then the result changes. The child’s creditors can also reach the child’s interest, and the parent may not be able to sell alone.
The Land Owner Transparency Act adds one more document to the registration file. Each person who receives property under section 10(1), each transferee, must file a statement of transparency at the time that interest in land is registered. A parent who stays on title only to help a child get a mortgage may be holding that share as a bare trustee, which can require a transparency report under the Land Owner Transparency Act and federal bare trust reporting. Ask your lawyer to confirm before filing.
What Is the Youngest Age You Can Own a Property in Canada?
In Canada, there is no national minimum age for owning property; instead, each province decides that. In British Columbia, the Age of Majority Act says a person reaches the age of majority on turning 19, not 18. The Land Title Act contains no minimum age for being on title, though a trustee usually manages property for anyone under 19.
The Infants Act lets the Public Guardian and Trustee petition the court for infants who possess or are entitled to land. If you plan to give property to a minor child, ask a lawyer how to structure it. A family trust is one option for managing it until the child turns 19.
How Do I Transfer Property to a Family Member Tax-Free in Canada?
Moving a home to a family member tax-free is possible only when an exemption fits the facts. The main way to avoid capital gains tax is the principal residence exemption, which can remove the gain on a main home. The property must have been the owner’s personal residence and principal residence for the designated years. Generally, only one property per family unit can be designated for a given year.
The exemption applies to capital gains tax only, not to the other costs of the transfer. Property transfer tax, legal fees, and the fee from LTSA fee can still be applicable depending on the facts. If part of the home earned rental income, the exemption may shrink, so a tax advisor should review the use.
Consider a parent in Vancouver who has owned the house for 15 years and then gives it to their grown daughter. If the parent designates all 15 years, the Income Tax Act formula can eliminate the capital gain. Because the daughter is a Canadian citizen and the home was the parent’s principal residence for at least six continuous months immediately before the transfer, the family may also claim the property transfer tax exemption. The family still pays the LTSA fee and legal fees, and a Vancouver estate lawyer can confirm each condition before anyone signs.
How Long Does It Take To Complete a Property Transfer?
Registration at the LTSA typically takes 10 to 15 business days, and often only 2 business days for eligible online applications. That range covers the registry step only, not the preparation that comes before filing. The time before filing depends on the appraisal, any lender consent, the title searches, and how fast the family can sign things over.
Planning with an estate lawyer and a tax advisor usually shortens preparation, since delays surface before filing. A transfer that involves a mortgage or any kind of title issue takes longer than getting a house that has no mortgage at all as a gift.
Checklist for Parents and Children Before Transferring Property Ownership
Good preparation saves time, reduces legal fees, and sidesteps tax issues and legal hassles that crop up much later. The steps below follow the order that works for most families, starting with the title and ending with the filings.
First, verify ownership and liens. Order a title search to confirm the registered owner and to find any lien or charge on the title.
Next, gather the documents. Collect the title search, a recent property tax assessment, proof that property taxes are paid, and any will or trust documents.
Then seek professional advice. Meet an estate lawyer and tax professionals to understand the legal obligations and the tax the transfer may trigger.
Finally, complete the filings. Have your lawyer file the transfer and the property transfer tax return, then report the disposition on the tax return.
Key Documents Needed Before Transferring Property
Before transferring property from a parent to a child, gather proof of ownership and show that the property is in good condition. A title search shows the registered owner, the charges against the title, and any liens that must be cleared. If this transfer is part of estate planning, the will or trust documents specify who gets what and any conditions that apply.
The other paperwork includes the latest property tax assessment, proof that property taxes are paid, mortgage statements, and the appraisal. Having them ready helps your lawyer prepare accurate legal documents and avoids any delays.
Importance of a Clear Title and Resolving Existing Liens or Claims
Before transferring property, confirm that the title is free of liens, unpaid property taxes, and legal claims. Under section 184 of the Land Title Act, the transferor must be the registered owner before the child can be registered. A gap in the registered ownership has to be fixed first, and a title search costs $11.06 through the LTSA.
A lien or claim that surfaces after the transfer becomes the child’s problem as well as the parent’s. A real estate lawyer can settle outstanding balances, deal with lenders, and make sure that titles transfer smoothly. It’s much simpler to clear the title before you file something compared to having to fix a defect afterward.
Ready to Transfer Property to Your Child the Right Way?
The right way depends on the property, tax situation, and family considerations. A gift is a deemed sale, a below-market sale risks double taxation, and a joint title invites a resulting trust claim. Talking to a lawyer briefly before signing something usually feels better than trying to straighten out later if you’ve messed up a transfer.
Onyx Law Group represents clients throughout British Columbia in family law, estate and trust litigation, estate planning, and probate. Our experienced estate and trust lawyers review the title, the tax result, and the family circumstances before a transfer is signed, and we serve clients from Kerrisdale, downtown Vancouver, and New Westminster. Contact us today to talk through your transfer matters with a lawyer.
Frequently Asked Questions
Our lawyers deal with family property transfers and the disputes that follow them, so the same questions come up often. The answers given below reflect current federal and BC rules. This is general information and should not be taken as personal advice for your specific property.
What Documents are Needed to Transfer Property From a Parent to a Child in Canada?
British Columbia requires a Form A Freehold Transfer, proof of ownership, a tax return for transferring property, and a declaration of transparency. A legal professional may also request a family gift affidavit, though BC’s official sources do not list it as required.
Are There Capital Gains Tax Implications When Gifting Property to My Child?
Yes, because gifts are treated under the Canada Revenue Agency as sales at their fair market value. The parent may owe tax on 50% of the taxable gain. The principal residence exemption can reduce or eliminate that tax when the property was the parent’s main home.
Can a Parent Transfer Property to a Child to Avoid Estate Taxes?
Canada has no estate tax, but at death the deceased is taxed on the deemed sale of capital property, and BC charges probate fees. A lifetime transfer does not avoid tax, because the gift is a deemed sale and capital gains tax can apply. Probate fees may be reduced, but the tax and control costs of the transfer can outweigh the savings.
Can Adding My Child to Title Avoid Probate Fees?
In some cases, there is an exception that allows parents’ shares to be moved out of the estate through something called a right of survivorship. The resulting trust presumption can pull the share back if the evidence does not show a gift. Child creditors and family law claims can also affect the child directly.
What Legal Disputes Can Arise From Transferring Property Between Family Members?
There are disputes about undue influence, unjust enrichment claims, ownership disputes, disagreements on valuations and lack of clear documentation regarding intentions of the parent. Siblings who feel excluded may also challenge the transfer after the parent dies.
How Long Does the Property Transfer Process Usually Take in Canada?
Most land titles register with the LTSA within 10 to 15 business days. Eligible online applications often register in 2 business days, while preparation before filing adds time.
Attorney Advertising. This page is promotional material from Onyx Law Group, a law firm with its office in Vancouver, British Columbia.
Disclaimer. The information here is general legal information regarding British Columbia and Canadian law; this is not legal advice for any specific case. Reading this page does not establish an attorney-client relationship. Laws differ based on provinces and personal situations, and tax rules change constantly. So you should talk to a qualified British Columbia estate lawyer and a tax professional for your specific case. Past results, illustrative scenarios, and reference to typical fact patterns do not guarantee similar outcomes in any specific case.